How banks and NBFCs use conversation monitoring to prevent compliance failures before they become complaints
Compliance failures in financial services conversations are typically discovered in the audit, weeks or months after the call. Here’s how automated monitoring changes the timeline.
By the OrySense team · · 7 min read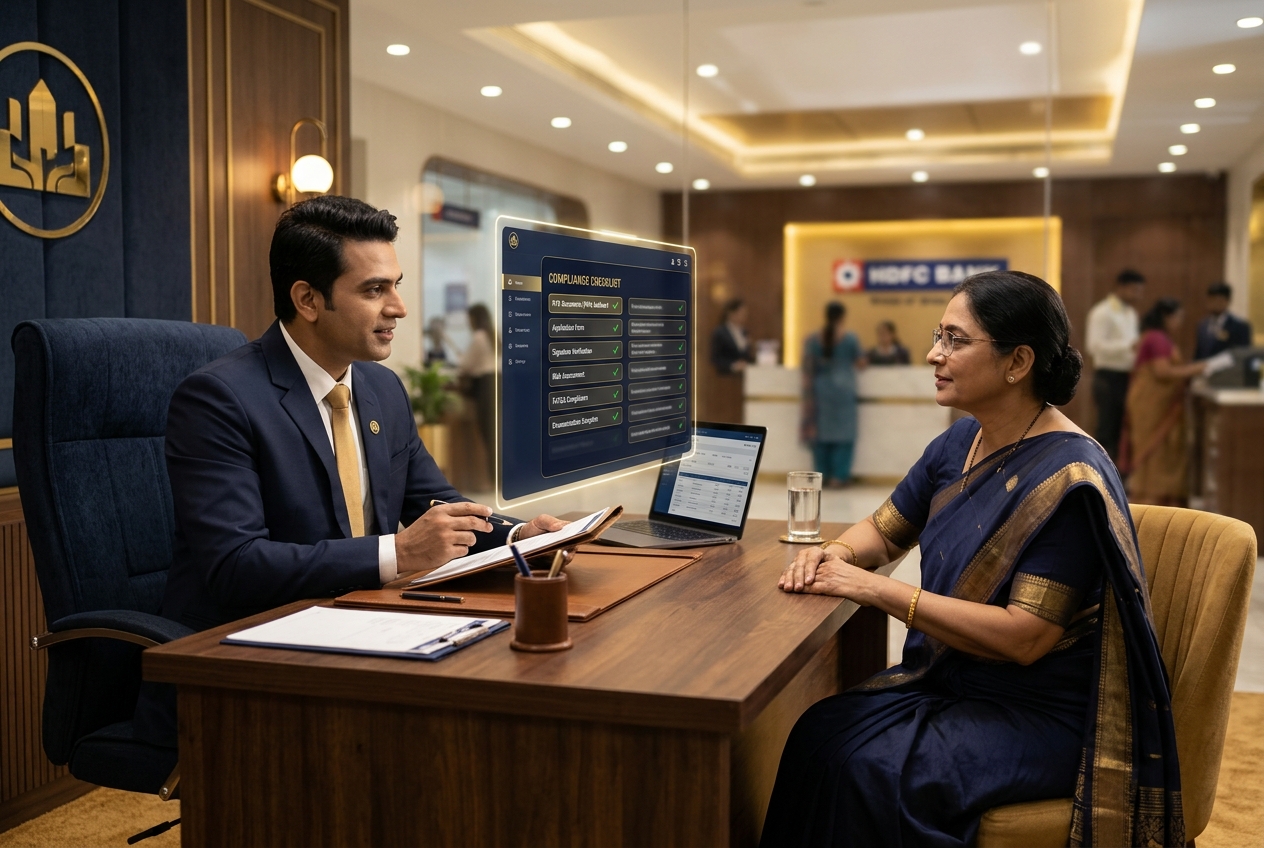
In financial services, a single conversation can create a regulatory liability. A loan officer who doesn’t mention the processing fee. An insurance agent who implies a guaranteed return. A collections agent who uses language outside policy. The standard way to catch these is a QA sample — a reviewer listening to 2% of calls, flagging issues and sending a report to compliance at the end of the month. By then, the customer may have filed a complaint.
Why the audit-lag is a structural problem
Compliance QA built on sampling has three weaknesses. **Coverage**: 98% of calls are never reviewed. A disclosure failure can happen hundreds of times before it’s caught. **Timing**: Issues surface in the next QA cycle, not the next day. **Evidence**: When a complaint arrives, finding the specific call requires searching through unindexed recordings. With automated processing, the call, its transcript and the exact moment of the breach are already structured and searchable.
What automated compliance monitoring looks like
Every conversation is processed against your compliance checklist as soon as it ends. For each call, OrySense checks which required disclosures were made and which were missed, whether any language matches your risk dictionary (guaranteed returns, misleading claims, coercive language), and whether the SOP for that product category was followed in the correct order. When a breach is detected, a Red SOS alert is raised and routed to the relevant compliance supervisor — with the call, transcript and the exact moment of the breach attached.
The day-one benefit
The most immediate change for BFSI teams moving from sampled QA to automated monitoring is alert timing. Instead of discovering that an agent missed a risk disclosure during last month’s QA cycle, the team leader sees it the same afternoon. In many cases, same-day discovery allows the agent to call the customer back, clarify the information and prevent a complaint from being filed. That option doesn’t exist when the issue surfaces weeks later.
Getting started
Most BFSI teams begin with their highest-risk product category — lending or investment advisory — where the regulatory consequences of a missed disclosure are greatest. Coverage can expand to other products and channels as confidence in the scoring grows.